The volantino playbook: how Italian retail sells the monthly offer
Sixteen Italian retailers, a year of launches, and the question every trade-marketing team asks each month: how do you put the offer on screen? 3,815 offer creatives from fifteen of them — grocery, discount, sport and pet — classified the same way: the offer, the price, the layout and the urgency.
What we found
- 014 playbooks
The market splits four ways
The sale event is the leading offer at six retailers (Lidl, PENNY, Bennet, MD, ALDI, Conad), % off at five (Arcaplanet, L'Isola dei Tesori, Zooplus, Carrefour, Coop), the hero price at three (Eurospin, Decathlon, Pam Panorama) — and Esselunga alone leads with the loyalty-card price. There is no single Italian volantino style.
- 0211 of 15
The date window is the grocery standard
Eleven retailers put a validity date on at least a third of their offer creatives — Esselunga on 83%. Scarcity cues are almost unused: "while stocks last" peaks at 4% (ALDI), and only Zooplus uses a countdown on more than 4% of creatives.
- 039 of 12
Hero-price creative is the kind that gets kept
Where there are enough of them to compare, hero-price creatives run at least as long as the retailer's typical creative at nine of twelve retailers — at Esselunga and Pam Panorama 14 days against 8. ALDI is the exception (4 vs 7). Sale events are not uniformly short-lived: they run about one flyer cycle, whatever the retailer's own rhythm.
- 0429% vs 54%
Digital creative drops the flyer
Where a retailer runs both, its digital creatives carry a validity date on 29% against 54% for its store-traffic creatives, and a flyer cover on 8% against 27% — lower at seven or more of ten retailers, higher at no more than one.
01The study
What we looked at
The volantino — the monthly (or fortnightly) offer flyer — is the heartbeat of Italian retail marketing, and on Meta it has become a stream of creatives: the flyer cover, the hero product at a price, the percentage off, the loyalty-card price, the weekend sale.
We tracked sixteen retailers across grocery, discount, sport and pet — from Lidl, Esselunga, Conad and Coop to Decathlon, Arcaplanet and L'Isola dei Tesori — and took every ad they launched between 29 September 2025 and 28 September 2026. One window for every number here.
The question is practical: if you are building next month's volantino creative, what are the recurring ways the market puts an offer on screen, and which of those creatives do retailers keep running?
Take it with you
Download this study as a PDF
Every chart and finding in this report, laid out for the deck you are building or the team you are forwarding it to.
- 56,684 ads
- 16 brands
- 3815 openings classified
- Methodology
Your brand in the set
Where would your brand sit on these charts?
We run this exact analysis with your brand in focus — against Arcaplanet, Lidl Italia, Decathlon Italia or whoever you actually compete with. Every video opening classified, every moment you trade on.
04The market
A third of retail creative carries no offer at all
How the fifteen analysed retailers build their creatives: the offer, how the price is shown, and the layout. Each retailer counts equally — the average of fifteen retailer mixes — so the retailers with bigger samples do not set the market.
Offer mechanic
This set leans No offer.
Price display
This set leans No price shown.
Layout
This set leans Text / graphic only.
When the offer is on screen it is a sale event or a percentage (19% each), then the hero price (11%). Half the creatives show no price, and when one is shown it is overwhelmingly a single big number: the hero number outnumbers the old-vs-new strikethrough six to one. The most common layout is not the flyer cover but a text / graphic card (31%).
05Retailer by retailer
Fifteen retailers, fifteen offer mixes
For each retailer, the most common offer mechanic and price treatment among creatives that show one, with its share of all that retailer's classified creatives; the share with no offer and no price at all; the most common layout; and the share carrying a validity date. Sorted by classified creatives.
| Retailer | Creatives | Lead offer | No offer | Lead price display | No price shown | Lead layout | Date window |
|---|---|---|---|---|---|---|---|
| Arcaplanet | 504 | % off · 36% | 9% | Hero number · 46% | 33% | Flyer cover / promo · 22% | 56% |
| PENNY Italia | 405 | Sale event · 33% | 30% | Hero number · 14% | 78% | Text / graphic only · 46% | 48% |
| L'Isola dei Tesori | 370 | % off · 42% | 6% | Hero number · 79% | 15% | Category banner · 39% | 42% |
| Zooplus | 359 | % off · 37% | 51% | Hero number · 27% | 58% | Single product / Category banner · 30% | 4% |
| Lidl Italia | 350 | Sale event · 40% | 23% | Hero number · 31% | 34% | Flyer cover / promo · 41% | 46% |
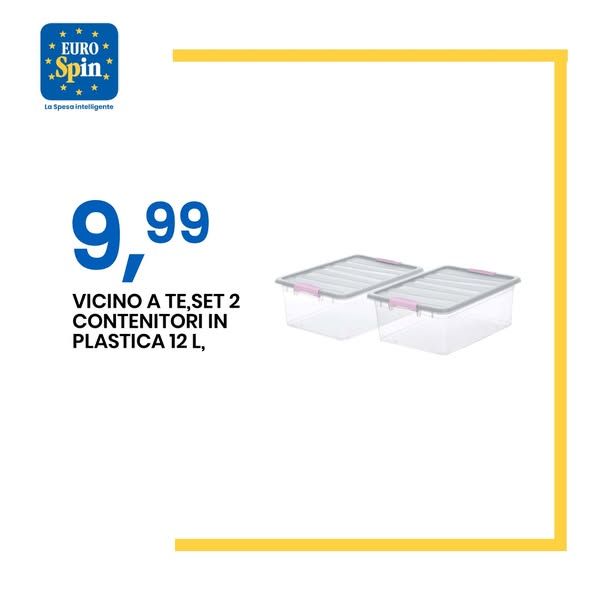
| Eurospin | 261 | Hero price · 22% | 40% | Hero number · 40% | 52% | Text / graphic only · 33% | 35% |
| Bennet | 241 | Sale event · 35% | 44% | Hero number · 20% | 76% | Text / graphic only · 43% | 44% |
| MD | 222 | Sale event · 15% | 61% | Hero number · 9% | 77% | Text / graphic only · 42% | 10% |
| Decathlon Italia | 213 | Hero price · 20% | 48% | Hero number · 36% | 54% | Single product · 42% | 7% |
| Esselunga | 190 | Loyalty / member price · 32% | 6% | Hero number · 50% | 25% | Flyer cover / promo · 29% | 83% |
| Carrefour Italia | 179 | % off · 24% | 35% | Hero number · 27% | 54% | Text / graphic only · 37% | 69% |
| ALDI Italia | 162 | Sale event · 28% | 36% | Hero number · 32% | 42% | Text / graphic only · 33% | 53% |
| Coop | 145 | % off · 27% | 50% | Hero number · 28% | 54% | Text / graphic only · 30% | 10% |
| Conad | 123 | Sale event · 28% | 32% | Hero number · 31% | 64% | Text / graphic only · 34% | 56% |
| Pam Panorama | 91 | Hero price · 41% | 16% | Hero number · 63% | 24% | Text / graphic only · 48% | 37% |
The hero number is the leading way to show a price at all fifteen retailers. What varies is how often a price is shown at all: 79% of L'Isola dei Tesori's creatives lead with one, against 9% at MD, where 77% show no price. Pam Panorama is the most hero-price retailer in the set (41% of its creatives).
06L'Isola dei Tesori
L'Isola dei Tesori sells the percentage, in numbers
How L'Isola dei Tesori's offer creatives are built — the most price-forward retailer in the set.
Offer mechanic
This set leans % off.
Price display
This set leans Hero number.
Layout
This set leans Category banner.
Almost everything is an offer (only 6% carry none), and 79% put a hero number on screen. It is also the set's heaviest user of multibuy (16%), with gift / free (11%) close behind — the pet-retail toolkit of "buy two" and "free with".
07Lidl Italia
Lidl sells the event and the flyer
How Lidl Italia's offer creatives are built.
Offer mechanic
This set leans Sale event.
Price display
This set leans No price shown.
Layout
This set leans Flyer cover / promo.
Lidl advertises the occasion more than the price: 40% of its creatives are a sale event, 41% are laid out as a flyer cover, and a third show no price at all.
08Esselunga
Esselunga sells the member price
How Esselunga's offer creatives are built.
Offer mechanic
This set leans Loyalty / member price.
Price display
This set leans Hero number.
Layout
This set leans Flyer cover / promo.
The only retailer whose leading offer is the loyalty-card price (32%), and one of the most price-forward: half its creatives lead with a hero number and a fifth carry a price badge — the set's highest. Lifestyle imagery is almost absent (1%).
09MD
MD sells the store, not the price
How MD's classified creatives are built — the opposite end of the set.
Offer mechanic
This set leans No offer.
Price display
This set leans No price shown.
Layout
This set leans Text / graphic only.
A discounter that mostly does not advertise the discount: 61% of MD's creatives carry no offer and 77% show no price. It also turns creative over fastest — its typical creative runs 3 days, the shortest in the set.
10The formats, as they ran
Six ways to put the offer on screen
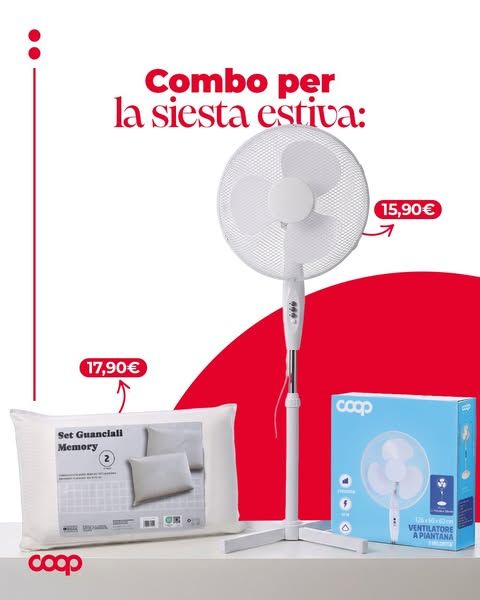
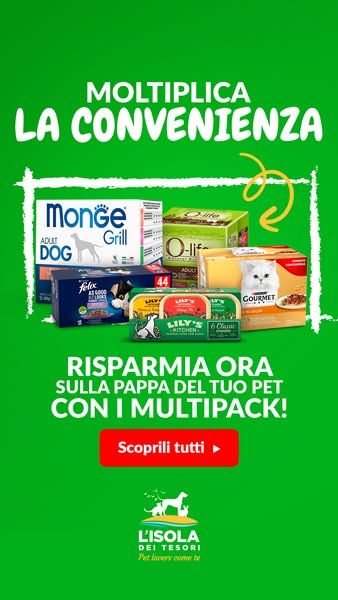
For each layout, the two longest-running distinct creatives from different retailers — among 1,128 text / graphic cards, 766 flyer covers, 686 single products, 522 category banners, 491 lifestyle creatives and 222 product grids. Run length is how long an ad stayed live, not a measure of results.
11Urgency
Grocery dates the offer; almost nobody counts down
Share of each retailer's classified creatives by the urgency cue on the creative.
| Retailer | Date window | Countdown / last days | While stocks last | None | Creatives |
|---|---|---|---|---|---|
| Esselunga | 83% | 0% | 1% | 16% | 190 |
| Carrefour Italia | 69% | 0% | 0% | 31% | 179 |
| Arcaplanet | 56% | 2% | 0% | 42% | 504 |
| Conad | 56% | 2% | 0% | 42% | 123 |
| ALDI Italia | 53% | 0% | 4% | 43% | 162 |
| PENNY Italia | 48% | 2% | 1% | 49% | 405 |
| Lidl Italia | 46% | 4% | 0% | 50% | 350 |
| Bennet | 44% | 1% | 0% | 56% | 241 |
| L'Isola dei Tesori | 42% | 1% | 2% | 54% | 370 |
| Pam Panorama | 37% | 0% | 0% | 63% | 91 |
| Eurospin | 35% | 0% | 0% | 64% | 261 |
| MD | 10% | 1% | 0% | 88% | 222 |
| Coop | 10% | 1% | 1% | 88% | 145 |
| Decathlon Italia | 7% | 0% | 0% | 93% | 213 |
| Zooplus | 4% | 14% | 2% | 81% | 359 |
The validity date — "dal 3 al 16 ottobre" — is the grocery default: 83% at Esselunga, 69% at Carrefour, a third or more at eleven retailers. The ones that skip it are the non-grocers and two grocers: Zooplus, Decathlon, Coop and MD date 10% or fewer. Countdowns matter at one retailer only — online-first Zooplus (14%) — and while stocks last never passes 4%.
12Retail vs digital
Store traffic or the online shop?
Retailers plan, budget and brief store traffic and e-commerce separately, so we tagged every ad in the window with the channel it sells: retail — it sends you to a store (the flyer, an opening, "ti aspettiamo") — digital — the online shop, the app, home delivery, a promo code — omnichannel — it names both ("in negozio e online", order online and collect in store) — or no channel cue at all (brand films, content, recruiting).
The tag comes first from what the ad says and where its link goes, then from the creative itself (the image or opening frame, read by our vision model), and only last from who it targets: an ad aimed at the towns around stores is counted as retail, but marked as inferred. Excluding Conad, 53% of the ads with a channel state it in the ad, 10% show it in the creative and 37% rest on targeting alone.
Across the fifteen retailers other than Conad, 58% of the 15,282 ads are retail, 19% digital, 7% omnichannel and 16% carry no channel cue — almost the same on distinct creatives (58% / 18% / 6% / 18%). The retail majority leans on targeting: only 38% of retail ads say so themselves, and Esselunga — 96% retail — is almost entirely inferred.
13Retail vs digital
What each retailer's ads sell: the store or the online shop
Share of each retailer's ads launched Sep 2025 – Sep 2026 by the channel they sell, and how the channel was established: stated in the ad (copy, link title or destination), read from the creative, or inferred from local targeting only — as a share of the ads that have a channel. The last column is the most common online route among the digital and omnichannel ads (withheld under 30 ads). Conad is shown last.
| Retailer | Ads launched | Retail | Digital | Omnichannel | No channel cue | Evidence · stated in the ad | Evidence · read from the creative | Evidence · targeting only | Lead online lever |
|---|---|---|---|---|---|---|---|---|---|
| Esselunga | 3,400 | 96% | 4% | 0% | 0% | 6% | 5% | 89% | Home delivery · 48% |
| Lidl Italia | 1,925 | 51% | 12% | 7% | 30% | 82% | 6% | 11% | App · 63% |
| Arcaplanet | 1,762 | 74% | 15% | 2% | 9% | 55% | 20% | 25% | Online shop · 62% |
| Eurospin | 1,146 | 20% | 43% | 33% | 4% | 94% | 5% | 1% | Home delivery · 67% |
| PENNY Italia | 1,141 | 44% | 7% | 1% | 48% | 66% | 31% | 2% | App · 65% |
| MD | 1,029 | 66% | 6% | 3% | 25% | 80% | 5% | 14% | Online shop · 76% |
| Decathlon Italia | 1,025 | 20% | 9% | 8% | 63% | 73% | 7% | 21% | App · 59% |
| Zooplus | 918 | 0% | 100% | 0% | 0% | 100% | 0% | 0% | Online-only retailer |
| Bennet | 910 | 58% | 13% | 12% | 17% | 41% | 18% | 41% | Home delivery · 38% |
| L'Isola dei Tesori | 419 | 19% | 56% | 21% | 4% | 94% | 6% | 0% | Online shop · 42% |
| Carrefour Italia | 407 | 49% | 12% | 34% | 5% | 58% | 24% | 18% | Online shop · 98% |
| Coop | 388 | 87% | 6% | 0% | 7% | 15% | 22% | 64% | — |
| ALDI Italia | 373 | 95% | 3% | 2% | 0% | 50% | 11% | 39% | — |
| Pam Panorama | 309 | 78% | 19% | 2% | 1% | 46% | 0% | 54% | Home delivery · 91% |
| Robinson Pet Shop | 130 | 8% | 62% | 19% | 11% | 93% | 3% | 4% | Online shop · 78% |
| Conad | 41,402 | 92% | 1% | 6% | 1% | 52% | 1% | 48% | Home delivery · 59% |
Digital and omnichannel ads are the majority at three retailers: Zooplus (100%), L'Isola dei Tesori (76%) and Eurospin (76%) — Eurospin the only grocer among them, on the back of its home-delivery and online-store programme. Online, retailers take two routes: the app leads the digital and omnichannel ads at PENNY Italia, Lidl Italia and Decathlon Italia; home delivery at Pam Panorama, Eurospin, Conad, Esselunga and Bennet. Conad is 7% online — but that is 2,971 ads, more than any other retailer, mostly its online grocery service advertised store by store.
14Retail vs digital
The flyer stays in the store
How classified creatives are laid out, by the channel they sell. Each retailer counts equally, among retailers with at least 20 classified creatives in that channel — fourteen for retail, eleven for digital (Zooplus included), six for omnichannel — so the three cards are not the same retailers; the like-for-like comparison is in the next table.
Retail · 14 retailers
This set leans Text / graphic only.
Digital · 11 retailers
This set leans Text / graphic only.
Omnichannel · 6 retailers
This set leans Text / graphic only.
The flyer cover is 25% of retail creative and 24% of omnichannel, but 8% of digital; digital leans on the text / graphic card (41%) and lifestyle + offer (19% against 10% for retail).
15Retail vs digital
Same retailer, two channels: what changes in the creative
The ten retailers with at least 20 classified retail and 20 digital creatives (Lidl Italia, Eurospin, L'Isola dei Tesori, Arcaplanet, Bennet, Decathlon Italia, PENNY Italia, Esselunga, MD and Pam Panorama). Shares are the average of the ten retailer shares, each retailer weighted equally. "Digital vs retail" counts the retailers where the digital share is at least 10 points lower or higher. The last column repeats the comparison on creatives whose channel is stated in the ad only (six retailers qualify).
| On the creative | Retail | Digital | Digital vs retail · 10 retailers | Stated channel only · retail / digital |
|---|---|---|---|---|
| Validity date on the creative | 54% | 29% | lower at 7 · higher at 1 | 68% / 23% |
| Flyer cover / promo layout | 27% | 8% | lower at 7 · higher at 1 | 35% / 5% |
| Lifestyle + offer layout | 9% | 19% | lower at 1 · higher at 5 | 2% / 26% |
| No price shown | 44% | 54% | lower at 1 · higher at 5 | 29% / 47% |
| Sale event | 24% | 10% | lower at 6 · higher at 1 | 31% / 9% |
| Loyalty / member price | 10% | 13% | lower at 1 · higher at 1 | 7% / 20% |
| No offer | 25% | 34% | lower at 1 · higher at 4 | 10% / 21% |
| Hero number price | 40% | 36% | lower at 3 · higher at 2 | 50% / 42% |
| % off | 18% | 12% | lower at 4 · higher at 1 | 23% / 11% |
Digital creative is not the flyer moved online. It carries a validity date on 29% of creatives against 54% for retail (lower at seven of ten retailers, higher at one: Arcaplanet) and uses the flyer-cover layout on 8% against 27% (lower at seven, higher at one: Decathlon Italia). The sale event is mostly a store mechanic (24% vs 10%, lower online at six retailers — Arcaplanet the exception). The pattern holds when only creatives whose channel is stated in the ad are counted (six retailers, last column).
16Retail vs digital
Retailer by retailer: retail / digital
Each cell is retail / digital for the same retailer: classified distinct creatives, share with a validity date, share laid out as a flyer cover, share of lifestyle + offer, share showing a loyalty / member price, and median run length in days (how long the retailer kept the creative live, not a measure of results).
| Retailer | Creatives | Date window | Flyer cover | Lifestyle + offer | Loyalty price | Median days |
|---|---|---|---|---|---|---|
| Arcaplanet | 301 / 150 | 49% / 82% | 25% / 25% | 5% / 38% | 7% / 8% | 6 / 3 |
| PENNY Italia | 289 / 30 | 56% / 20% | 28% / 10% | 5% / 13% | 29% / 37% | 10 / 10 |
| L'Isola dei Tesori | 71 / 220 | 82% / 16% | 11% / 1% | 0% / 16% | 14% / 5% | 5 / 5 |
| Lidl Italia | 222 / 38 | 57% / 34% | 61% / 11% | 8% / 37% | 0% / 47% | 7 / 8 |
| Esselunga | 166 / 20 | 87% / 55% | 32% / 10% | 1% / 0% | 34% / 15% | 8 / 14 |
| Bennet | 159 / 21 | 48% / 29% | 29% / 14% | 4% / 10% | 7% / 5% | 6 / 5 |
| MD | 132 / 26 | 10% / 12% | 20% / 0% | 2% / 19% | 6% / 8% | 5 / 3 |
| Eurospin | 94 / 61 | 79% / 10% | 53% / 2% | 10% / 15% | 0% / 0% | 6 / 20 |
| Pam Panorama | 61 / 25 | 51% / 8% | 11% / 0% | 8% / 20% | 3% / 0% | 7 / 29 |
| Decathlon Italia | 29 / 37 | 17% / 22% | 0% / 11% | 52% / 22% | 0% / 5% | 27 / 10 |
At Lidl the digital creative is the loyalty programme: 47% of its digital creatives show a member price (the Lidl Plus app), against 0% of its retail ones. Run length has no single direction: Eurospin (20 days vs 6) and Pam Panorama (29 days vs 7) keep digital creatives far longer — always-on service ads for the online shop — while Arcaplanet, MD and Decathlon Italia turn digital creative over faster than retail.
17Retail vs digital
Three channels, as they ran
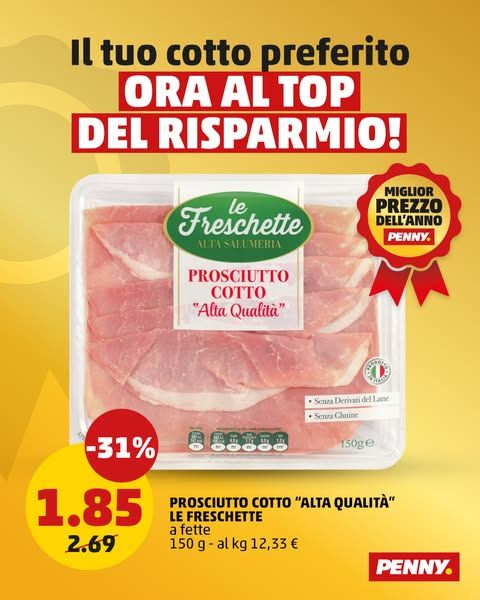
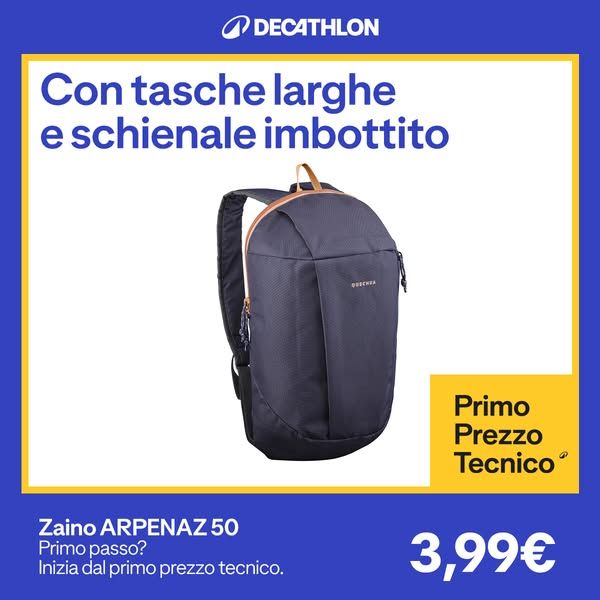
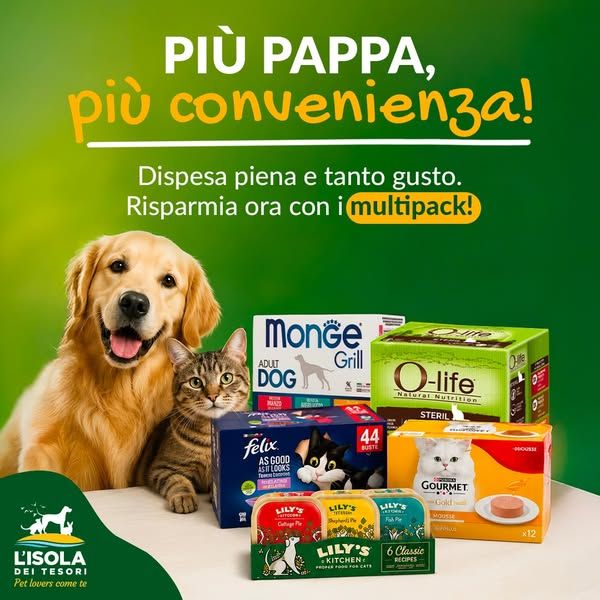
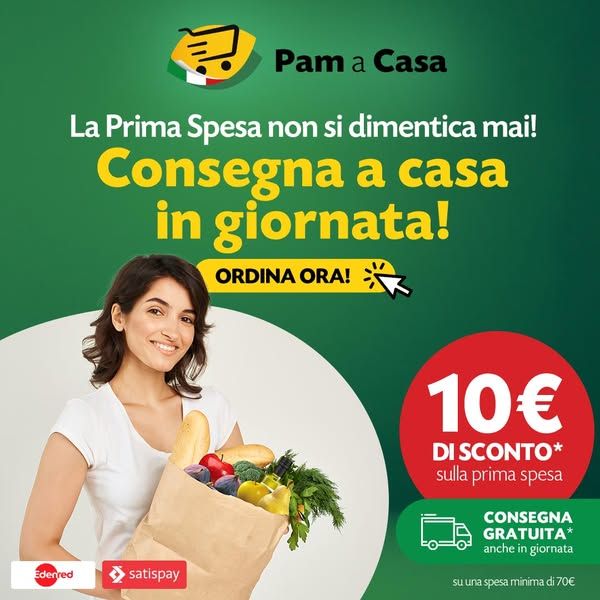
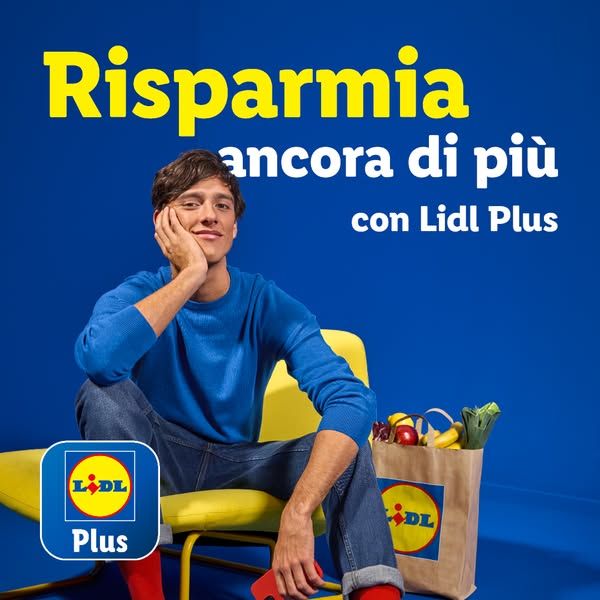
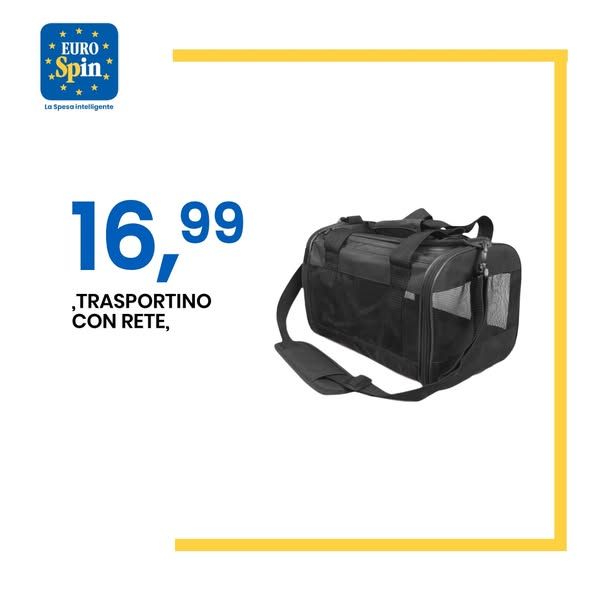
For each channel, the two longest-running classified offer creatives whose channel is stated in the ad, each from a different retailer. Run length is how long an ad stayed live, not a measure of results.
18What lasts
Which offers retailers keep running
Median run length in days of each retailer's classified creatives, by offer mechanic (n in brackets). Compare each cell with the same row's "All" column — run lengths differ a lot between retailers (3 days at MD, 14 at Zooplus and Decathlon), so compare within a retailer, not across. Cells under 10 creatives are withheld (—); differences of a day or two are noise.
| Retailer | All | % off | Price cut | Hero price | Multibuy | Loyalty / member price | Gift / free | Sale event | No offer |
|---|---|---|---|---|---|---|---|---|---|
| Arcaplanet | 6 (504) | 5 (180) | — | 6 (34) | 7 (73) | 3 (32) | 8 (15) | 4 (115) | 7 (46) |
| PENNY Italia | 10 (405) | 12 (19) | — | 11 (13) | — | 11 (98) | 11 (11) | 11 (132) | 7 (122) |
| L'Isola dei Tesori | 6 (370) | 5 (157) | 3 (16) | 5 (25) | 6 (58) | 15 (31) | 9 (41) | 25 (21) | 11 (21) |
| Zooplus | 14 (359) | 13 (134) | — | — | — | — | — | 6 (22) | 17 (184) |
| Lidl Italia | 6 (350) | 5 (51) | 6 (16) | 6 (29) | — | 14 (29) | — | 7 (139) | 5 (80) |
| Eurospin | 13 (261) | — | 15 (12) | 16 (58) | — | — | 13 (28) | 11 (53) | 14 (105) |
| Bennet | 5 (241) | 13 (26) | — | — | — | 7 (12) | — | 12 (85) | 5 (105) |
| MD | 3 (222) | — | 7 (18) | 7 (14) | — | 3 (12) | — | 7 (33) | 3 (135) |
| Decathlon Italia | 14 (213) | 12 (32) | 8 (12) | 16 (42) | — | — | — | 7 (14) | 18 (103) |
| Esselunga | 8 (190) | 8 (44) | — | 14 (27) | — | 8 (61) | — | 7 (35) | 13 (12) |
| Carrefour Italia | 7 (179) | 8 (43) | — | — | 8 (18) | — | — | 8 (37) | 7 (63) |
| ALDI Italia | 7 (162) | 6 (24) | 6 (10) | 4 (17) | — | — | — | 7 (45) | 8 (59) |
| Coop | 6 (145) | 5 (39) | — | 6 (21) | — | — | — | — | 6 (73) |
| Conad | 10 (123) | 10 (21) | — | 9 (13) | — | — | — | 8 (34) | 12 (39) |
| Pam Panorama | 8 (91) | — | — | 14 (37) | — | — | 7 (17) | — | 11 (15) |
Hero price runs at or above its retailer's median at nine of twelve retailers — clearly so at Esselunga and Pam Panorama (14 days vs 8), Eurospin and MD — with ALDI the exception (4 vs 7). No-offer creatives are kept even more consistently: at or above the median at 13 of 15. Sale events are not simply short-lived: they run about a flyer cycle, so they sit below the median where creative runs long (Zooplus 6 vs 14, Decathlon 7 vs 14) and above it where it runs short (Bennet 12 vs 5). The loyalty price is kept at Lidl (14 vs 6) and L'Isola dei Tesori (15 vs 6).
19Motion
The flyer in motion
Video is where the flyer turns into a story. The longest-running offer videos in the classified sample, one per retailer.
20What lasts
Which layouts retailers keep running
The same read by layout: median run length in days (n in brackets), to be compared with the retailer's own median in the "All" column. Cells under 10 creatives are withheld (—).
| Retailer | All | Single product | Product grid | Flyer cover / promo | Lifestyle + offer | Category banner | Text / graphic only |
|---|---|---|---|---|---|---|---|
| Arcaplanet | 6 (504) | 3 (13) | 7 (109) | 5 (113) | 5 (97) | 5 (76) | 7 (96) |
| PENNY Italia | 10 (405) | 12 (46) | 9 (19) | 11 (108) | 11 (28) | 10 (16) | 8 (188) |
| L'Isola dei Tesori | 6 (370) | 6 (15) | — | 26 (27) | 7 (66) | 6 (143) | 5 (111) |
| Zooplus | 14 (359) | 16 (108) | — | 6 (19) | 15 (52) | 15 (108) | 12 (72) |
| Lidl Italia | 6 (350) | 6 (67) | — | 7 (145) | 6 (56) | 3 (20) | 6 (55) |
| Eurospin | 13 (261) | 21 (57) | 21 (23) | 7 (56) | 16 (21) | 21 (17) | 7 (87) |
| Bennet | 5 (241) | 5 (30) | — | 13 (71) | 4 (13) | 9 (20) | 5 (104) |
| MD | 3 (222) | 4 (61) | — | 7 (32) | 3 (20) | — | 3 (94) |
| Decathlon Italia | 14 (213) | 16 (90) | — | 9 (22) | 25 (50) | 11 (15) | 12 (36) |
| Esselunga | 8 (190) | 11 (49) | 7 (14) | 7 (56) | — | 14 (33) | 8 (37) |
| Carrefour Italia | 7 (179) | 8 (56) | — | 8 (30) | 7 (13) | 9 (14) | 7 (66) |
| ALDI Italia | 7 (162) | 5 (28) | 7 (16) | 7 (48) | 7 (15) | — | 8 (53) |
| Coop | 6 (145) | 6 (31) | — | — | 4 (25) | 6 (40) | 6 (43) |
| Conad | 10 (123) | 9 (19) | — | 9 (31) | 12 (22) | — | 11 (42) |
| Pam Panorama | 8 (91) | 7 (16) | — | — | 15 (12) | — | 10 (44) |
The flyer cover lives with the flyer: its median sits between 5 and 13 days at twelve of thirteen retailers, whatever their own rhythm — below the median at Zooplus, Eurospin and Decathlon, above it at Bennet and MD (L'Isola dei Tesori, at 26 days, is the exception). Single product and lifestyle + offer are the layouts most often kept — each at or above the median at 11 retailers — and lifestyle is Decathlon's long-runner (25 days vs 14).
21Price display
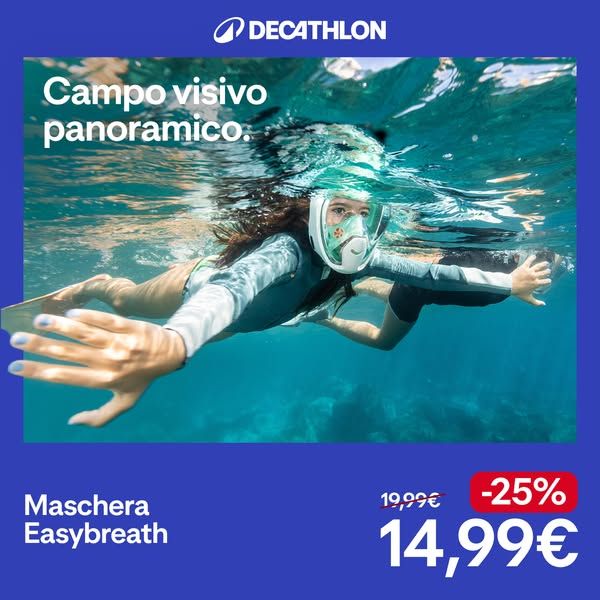
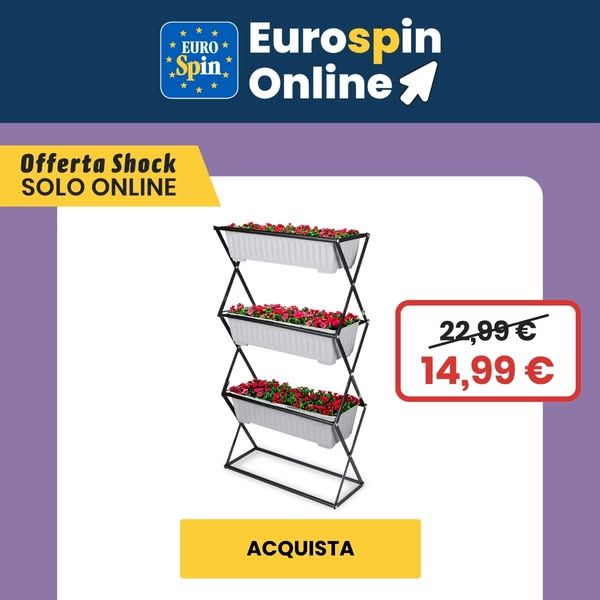
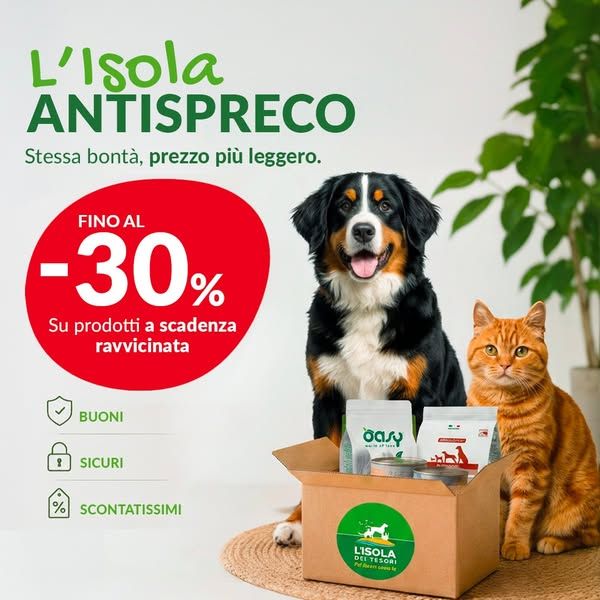
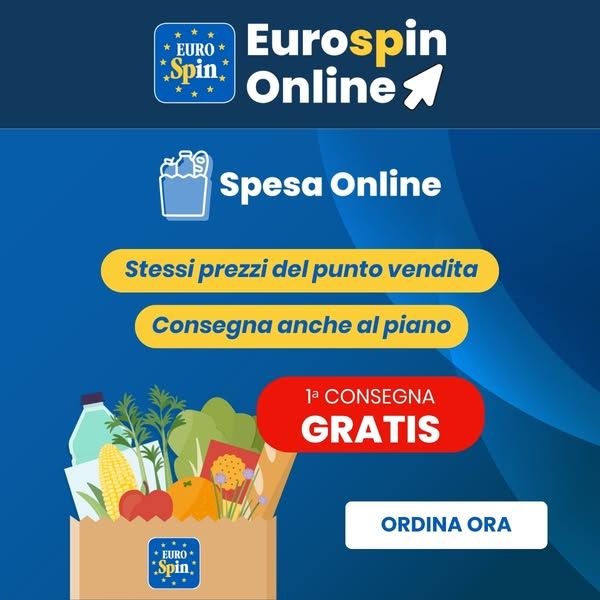
How the price is shown
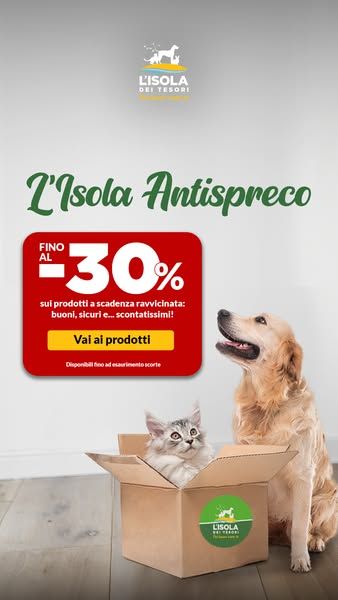
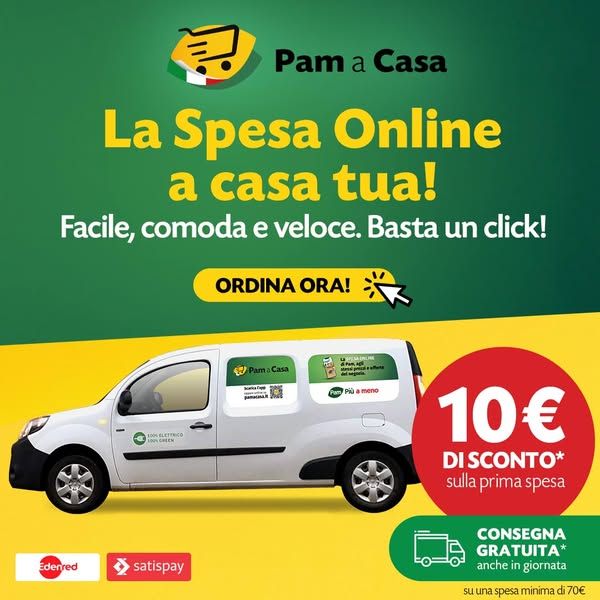
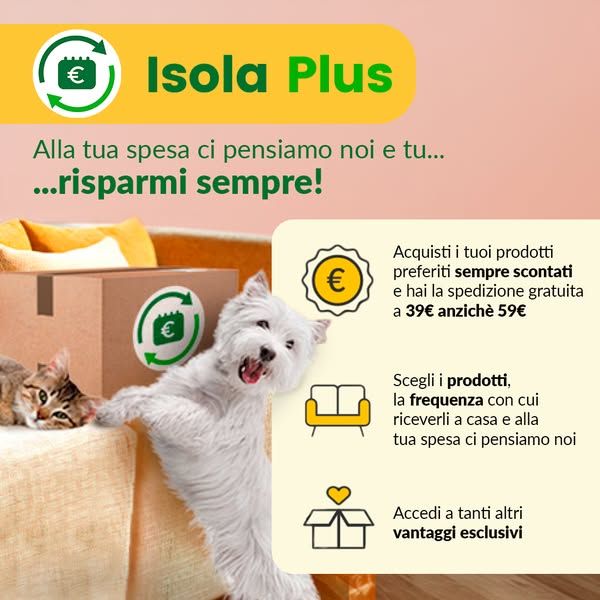
The three price treatments that recur across the set — the number as the hero, the old price struck through, and the badge on the pack — each with the longest-running still creatives from different retailers.
22For your next volantino
Three things worth reproducing
1. Put the dates on the creative. A validity window is how Italian grocery signals urgency — 83% of Esselunga's creatives carry one, and a third or more at eleven of fifteen retailers. Countdowns and "while stocks last" are almost entirely unused outside Zooplus, which makes them the obvious thing to test for a short, high-stakes offer.
2. Lead with one number. When a price is shown, every retailer in the set most often makes it the hero — a single big figure — rather than an old-vs-new strikethrough (17% of creatives at most, at Carrefour). L'Isola dei Tesori puts a hero number on 79% of its creatives, Pam Panorama on 63%, Esselunga on half.
3. Build two sets, not one. Sale-event and flyer-cover creatives run about one flyer cycle — a median of roughly a week — and are switched off with it. The creatives retailers keep past the cycle are the hero-price, single-product and no-offer ones: at or above their retailer's median at 9 of 12, 11 of 15 and 13 of 15 retailers. Plan a short-life flyer set for the fortnight and a smaller evergreen set — one product, one price, or the brand itself — built to run past it.
More studies
All published studies →Premium outerwear does not discount for Black Friday. It launches.
Premium Outerwear — Italy · Black Friday / Cyber 2025 · 8 min read
Four fashion markets, four Black Fridays
Fashion, four segments — Italy · Black Friday / Cyber 2025 · 8 min read
When does Black Friday start? Four industries, one calendar
Fashion, Beauty, Pet, Grocery — Italy · Black Friday / Cyber 2025 · 10 min read
How this was built
Set: Arcaplanet, Lidl Italia, Decathlon Italia, Esselunga, Conad, Eurospin, PENNY Italia, MD, Coop, Carrefour Italia, ALDI Italia, Bennet, Pam Panorama, Zooplus, L'Isola dei Tesori, Robinson Pet Shop. Window: 29 September 2025 – 28 September 2026. Source: Meta Ad Library (EU).
Ads were collected from the public Meta Ad Library for the EU, scoped to sixteen retailers active in Italy (two Data Room sets: Italian pet retail and Italian GDO & retail). Every figure uses one window: ads that **launched** between 29 September 2025 and 28 September 2026. Data snapshot: 29 September 2026.
**The classified creatives are a sample, not every ad.** The offer classification — offer mechanic, price display, layout and urgency, each a fixed Data Room taxonomy — was run on a capped, prioritised sample per retailer: up to about 400 stills and 150 videos, Black Friday and Christmas 2025 creatives first, then the ones that reached most people. Only retailers with at least 80 classified distinct creatives are analysed: 15 of 16, from Arcaplanet (504) to Pam Panorama (91); Robinson Pet Shop (44) is withheld. Because of the priority order the sample leans towards November–December 2025 — 46% of Lidl's and Decathlon's classified creatives launched then, against 16–20% of their ads, and all of Conad's — and its media mix follows the cap (Arcaplanet's and L'Isola dei Tesori's are almost all stills; Esselunga's mostly video).
Market-wide mixes are the average of the fifteen retailer mixes, each retailer weighted equally. Conad's classified sample is included there, but Conad is kept out of every ad-volume figure.
Creative claims are made on **distinct creatives**: ads carrying the same film (same video hash, or the same classified opening including known duplicates) or the same image (same perceptual hash) are collapsed to one, so a creative re-run across stores or audiences counts once. Ad counts are used for volume only.
Offer share from copy is an **estimate**: a case-insensitive keyword match on the ad text, link title and caption for volantino, offert-, scont-, promo, sottocosto, prezz-, risparmi-, 3x2, omaggio, % and €. It over-counts ("100% italiano") and misses offers that appear only in the image. Distinct texts ignore numbers, so the same message with a different price counts once.
Run length is the longest delivery of any ad carrying a creative, measured to the snapshot date for creatives still live (about 2% of classified creatives). Longer-running means the retailer kept it; it is not a measure of sales. Medians are rounded to whole days, and differences of a day or two should not be read as a result. Percentages in the mix cards are rounded to sum to 100.
**Channel.** Every ad in the window is tagged retail, digital, omnichannel or none by fixed rules: first the ad copy and link title ("in negozio", "ti aspettiamo", "volantino" vs "online", "app", "consegna a casa", promo codes; both = omnichannel), then the destination (a store locator vs an online shop, delivery site or app store), and Zooplus is treated as online-only. Where the text is silent, the creative itself is read by a vision model; only if both are silent does local targeting (a list of towns rather than all of Italy) count the ad as retail, marked as inferred. Explicit text always wins over the creative, and the creative over targeting.
A distinct creative takes the majority channel of its ads with the strongest evidence. Retail-vs-digital comparisons use only retailers with at least 20 classified creatives in each channel, each retailer weighted equally, and are repeated on stated-channel creatives only.
Cuts backed by fewer than 10 creatives are withheld throughout.
Your offer, your market
See this for your own retailer set
We build these for a specific retailer against a specific competitive set — every offer creative classified the same way, month by month. Tell us who you want to look at and we will set up a data room for you.